GIFT City vs Traditional NRI Investment Routes: A Comparison
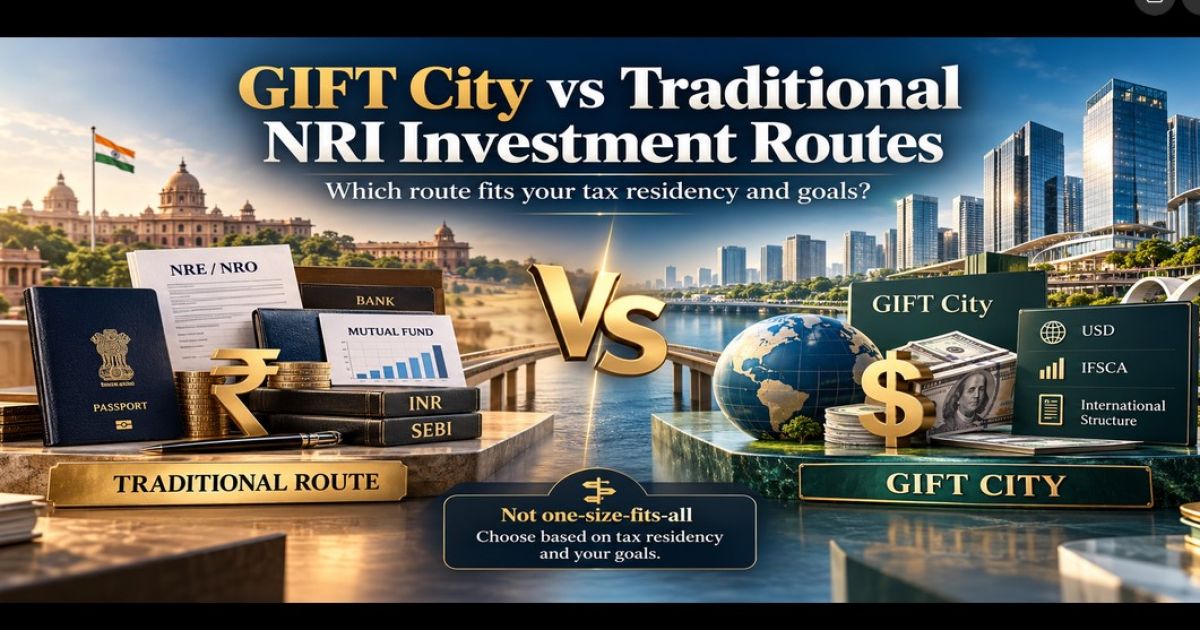
NRIs typically invest in India through
NRE/NRO-linked mutual fund accounts, or through newer GIFT City-based
structures. Neither is universally "better" — the right fit depends
on residency, tax obligations, and goals.
Structural Differences
|
|
Traditional
(NRE/NRO) Route |
GIFT City Route |
|
Regulator |
SEBI
(domestic mutual funds) |
IFSCA
(distinct framework) |
|
Currency |
Typically
INR |
Often
USD-denominated |
|
Common use
case |
General NRI
investing into Indian mutual funds |
Investors
seeking structures relevant to specific home-country tax treatment, e.g., US
PFIC considerations |
|
Reporting
complexity for US NRIs |
Often
triggers PFIC reporting |
Structured
differently — evaluate with a US tax advisor |
When the
Traditional Route Still Makes Sense
For many NRIs — particularly those
without US tax residency complications — the standard NRE/NRO mutual fund route
remains straightforward, well-understood, and sufficient.
When GIFT City Is Worth Evaluating
- US-based NRIs concerned about PFIC reporting
complexity (see our PFIC guide)
- Investors preferring USD-denominated structures
- Those seeking access to products structured
specifically for international capital
This is a structural comparison, not a
recommendation that either route fits your specific situation — that depends on
your residency and tax obligations.
Frequently
Asked Questions
Is GIFT City better than NRE/NRO
investing?
Neither is universally better — it
depends on your tax residency, reporting obligations, and goals. US-based NRIs
facing PFIC complications may find GIFT City structures worth evaluating; others
may not need to change their approach.
Can I use both routes
simultaneously?
Many NRIs do hold investments across
both structures, depending on the specific goal each is meant to serve. This
should be planned individually.
Do I need a different bank account
for GIFT City investing?
GIFT City structures generally involve
their own account-opening process, distinct from a standard NRE/NRO account —
see our step-by-step guide.
The Bottom Line
Don't choose based on which sounds more
sophisticated — choose based on your specific tax residency and reporting
obligations, ideally with both an investment advisor and a tax professional in
your country of residence.
Would you
like to understand how this applies to your financial goals? Connect with
Vikalpa Finvest for a structured discussion about your goals, investment
horizon, risk profile and existing portfolio.
Call: 98240
40666 | Email: mf@ashokindia.com
Compliance
disclaimer: Mutual fund investments are subject to market risks. Read all
scheme-related documents carefully. Calculations and assumed returns are for
illustration and educational purposes only. Actual returns may vary and are not
guaranteed. This article does not constitute tax advice for any specific
jurisdiction — consult a qualified tax professional for your individual
circumstances.