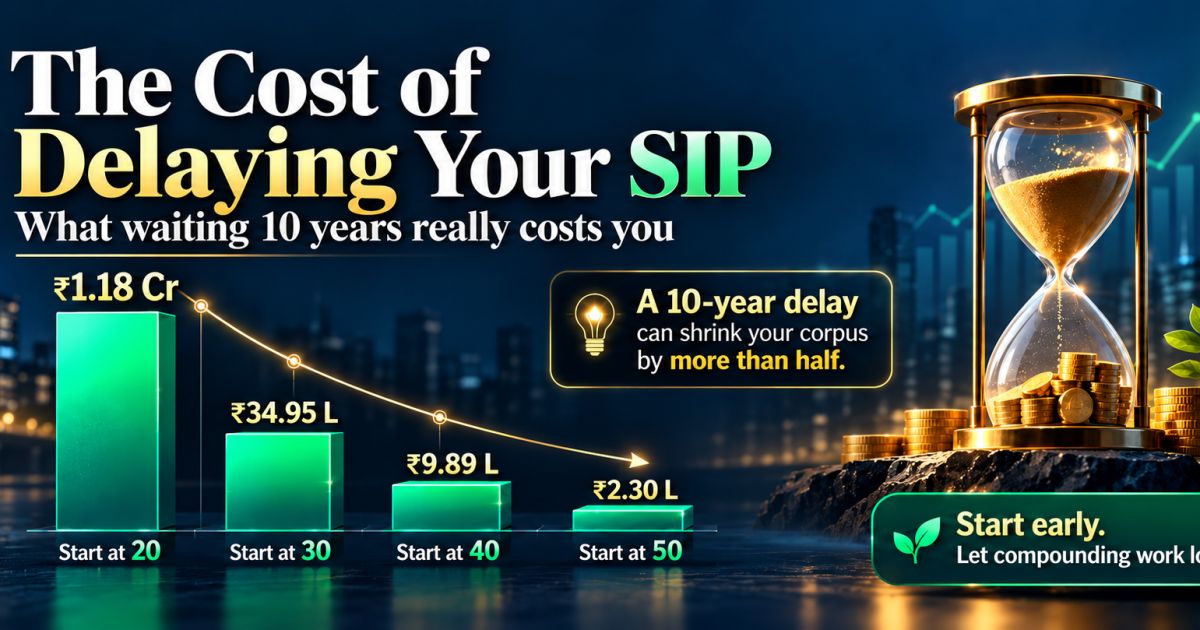
The Cost of Delaying Your SIP: What Waiting 10 Years Really Costs You
Introduction
Most investors know
they should start a SIP. Fewer realise what it actually costs to wait five,
ten, or twenty years to begin. It isn't a vague "you'll have less
money" — it's a specific, calculable number, and for most people, it's far
larger than they expect.
Quick answer (for readers in a hurry): A ₹1,000 monthly SIP started at age 20
and continued to age 60 can grow to roughly ₹1.18 crore at a 12% assumed annual
return — more than 25 times the actual amount invested. The same SIP started at
age 30 grows to only about ₹35 lakh. The ten-year delay doesn't cost you ten
years of contributions — it costs you more than half the final corpus, because
you lose the years where compounding does the most work.
This is the single most persuasive argument for starting
early, and it's worth understanding in rupee terms, not just in principle.
Why Delay Costs More Than It Looks Like
A SIP doesn't grow in a straight line. In the early years,
your monthly contributions are the main driver of growth. In the later years,
the returns on your earlier contributions start generating their own
returns — and that snowball effect is where most of the final corpus actually
comes from.
When you delay your SIP, you're not just skipping a few years
of contributions. You're skipping the years where compounding would have had
the most time to work on those specific contributions. That's why the
"cost of starting late" isn't proportional to the years missed — it's
disproportionately larger.
The Real Numbers:
Starting a ₹1,000 SIP at Different Ages
Here's what a ₹1,000 monthly SIP (continued until age 60)
actually produces, depending on the age you start — shown at three illustrative
return assumptions.
At an assumed 12% annual return:
|
Starting
Age |
Years
Invested |
Total
Invested |
Maturity
Value |
Growth
Multiple |
Cost
of Starting Late |
|
20 |
40 |
₹4,80,000 |
₹1,17,64,773 |
25x |
— (baseline) |
|
25 |
35 |
₹4,20,000 |
₹64,30,959 |
15x |
55% smaller |
|
30 |
30 |
₹3,60,000 |
₹34,94,964 |
10x |
54% smaller |
|
35 |
25 |
₹3,00,000 |
₹18,78,847 |
6x |
54% smaller |
|
40 |
20 |
₹2,40,000 |
₹9,89,255 |
4x |
53% smaller |
|
45 |
15 |
₹1,80,000 |
₹4,99,580 |
3x |
51% smaller |
|
50 |
10 |
₹1,20,000 |
₹2,30,039 |
2x |
46% smaller |
At an assumed 15% annual return, the same
pattern holds, but the gap widens further:
|
Starting
Age |
Maturity
Value |
Cost
of Starting Late |
|
20 |
₹3,10,16,055 |
— (baseline) |
|
25 |
₹1,46,77,180 |
47% smaller |
|
30 |
₹69,23,280 |
47% smaller |
|
35 |
₹32,43,530 |
47% smaller |
|
40 |
₹14,97,239 |
46% smaller |
|
45 |
₹6,68,507 |
45% smaller |
|
50 |
₹2,75,217 |
41% smaller |
At an assumed 20% annual return, the effect is even more
dramatic — the age-20 starter's corpus is over 6 crore, while the age-30
starter reaches roughly ₹2.3 crore, still less than a third.
Note: These figures
use a flat ₹1,000/month contribution purely to isolate the effect of starting
age. In practice, most investors increase their SIP amount over time, and
actual returns will vary with market conditions and fund selection — see the
disclaimer below.
The Pattern That Matters Most
Look at the "cost of starting late" column at 12%
returns: someone who starts at 25 instead of 20 — just a five-year delay — ends
up with a corpus that's 55% smaller. That's not five years' worth of
contributions missing. It's over half the final wealth, gone, because those
five years were the ones compounding needed most.
This is why financial advisors emphasise starting age
over starting amount. A smaller SIP started early consistently
outperforms a larger SIP started late, given enough time.
"But I Can
Just Invest More Later to Catch Up"
This is the most common objection, and it's mathematically
weaker than it feels. To match what an age-20 starter achieves with ₹1,000/month,
an age-30 starter would need to invest roughly three times as much every month
for the remaining 30 years — not because the math is unfair, but because
they're trying to compress 40 years of compounding into 30.
Catching up is possible. It's just far more expensive than
not falling behind in the first place.
What to Do If
You've Already Delayed
If you're reading this
at 35 or 45 and haven't started, the data above isn't meant to be discouraging
— it's meant to make the decision urgent rather than optional.
- Start now, at whatever amount you can commit to consistently.
The cost of the next year of delay is always higher than the cost of starting
imperfectly today.
- Reassess your monthly SIP amount against your actual goal,
rather than an arbitrary round number. A goal-based calculation (see our guide
on child education planning) will tell you what you actually need to invest.
- Consider a higher equity allocation if your time horizon
still allows it — see our asset allocation guide for how this typically shifts
with age.
- Don't let the "I've already lost time" feeling stop
you from starting at all. The data shows delay is costly — it doesn't show that
starting late is pointless.